
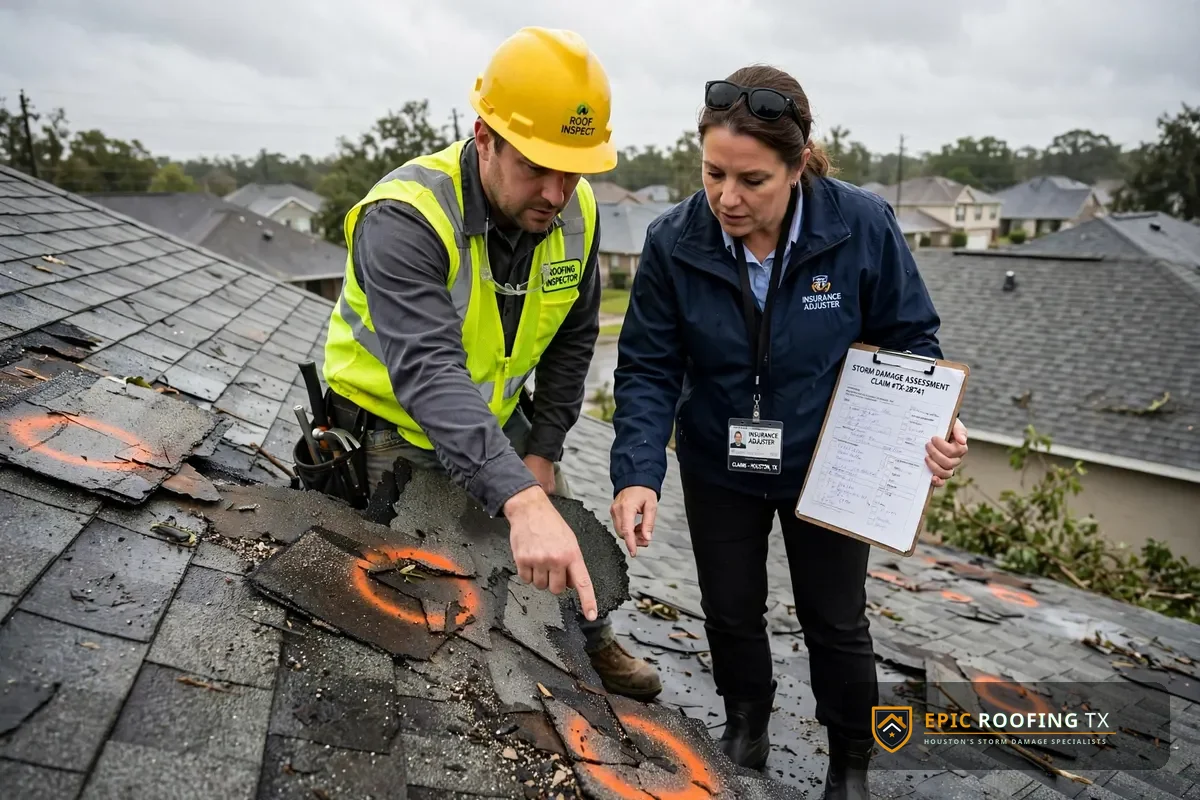
Direct Answer: What Does a Roof Insurance Claim Specialist Do?
A roof insurance claim specialist is the documentation expert on your side of the claim. They inspect your roof after a storm, photograph and chalk-mark every damaged slope, verify the storm date against weather records, write a line-item scope of the damage, and meet the insurance company's adjuster on your roof so nothing gets missed. They are not the insurance adjuster (who works for your carrier) and they are not a public adjuster (a separate Texas license). Their job is evidence: making sure the damage that exists is the damage that gets documented.
After a Houston hailstorm or wind event, most homeowners file a claim and simply hope the process is fair. Then the adjuster spends 40 minutes on the roof, writes a scope that covers two slopes of a four-slope roof, and the check arrives for a fraction of a real replacement. The difference between that outcome and a fully documented claim is usually one thing: whether somebody who reads roofs for a living stood next to the adjuster with photos, chalk, and a written scope. That somebody is a roof insurance claim specialist.
Three Different Roles in a Texas Roof Claim — Do Not Confuse Them
- The insurance (staff or independent) adjuster is assigned by your carrier. Their job is to apply your policy to the damage they find. They work for the insurance company — politely, professionally, and within the carrier's guidelines.
- A public adjuster is a separate professional licensed by the Texas Department of Insurance to represent policyholders and negotiate settlements for a fee, usually a percentage of the claim. Only a licensed public adjuster may legally negotiate your claim on your behalf in Texas.
- A roof insurance claim specialist is a roofing professional who handles the physical evidence side: inspection, documentation, storm verification, scope writing, and being present at the adjuster meeting. A roofer cannot act as your public adjuster, and any roofer who promises to "negotiate your settlement" or guarantee an approval is promising something they cannot legally or honestly deliver.
Understanding those boundaries protects you twice: you get real documentation help, and you never hand your claim to someone operating outside Texas rules.
What a Claim Specialist Actually Does, Step by Step
- Forensic roof inspection: Every slope is walked and photographed — hail strikes, creased or lifted shingles, damaged flashing, soft-metal dents on vents and turbines that corroborate storm force, plus attic evidence of active leaks.
- Chalked test squares: On hail claims, specialists mark standard 10x10-foot test squares per slope and count verified hits. This is the same method adjusters use — arriving with it already done changes the tone of the meeting.
- Storm-date verification: Your claim lives or dies on whether a qualifying storm hit your address on a specific date. Specialists match your damage to recorded hail and wind events for your ZIP code, which is how "Kingwood roof claim" questions get answered with data instead of opinion.
- A written, line-item scope: Measurements, slope diagrams, and an itemized repair/replacement scope written in the same line-item language (Xactimate-style) that carrier estimates use — starter course, underlayment, drip edge, ridge, steep charges — so comparisons are apples to apples.
- Meeting the adjuster on the roof: The specialist walks every slope with the adjuster, pointing to the documented damage with the photo file in hand. Missed slopes and missed line items get caught in person, not in a month of emails.
- Supplement documentation: If the carrier's scope omits legitimate items, the specialist documents the difference with photos and measurements so the supplement request is evidence-based rather than argumentative.
- Completion paperwork: Final invoices and completion photos support release of the recoverable depreciation — the second check many homeowners never realize they must actively claim.

📋 Filing a Roof Claim in Houston or Kingwood? Start with a free documented inspection — photo file, test squares, and a written scope before the adjuster ever sets a ladder.
See how claim support works: Insurance Claim Roofing Houston service → or call (281) 326-9905.
Kingwood & Atascocita: Why Claims Here Get Complicated
Kingwood's famous tree canopy is also its claims problem. Towering pines drop limbs in every serious wind event — the May 2024 derecho and Hurricane Beryl both tore through the Livable Forest — and punctures and impact damage hide under the same shade that makes the neighborhoods beautiful. Three local complications show up again and again:
- Concealed damage under debris: Pine straw and leaf litter sit on Kingwood roofs for weeks after a storm, hiding creased shingles and small punctures until they become ceiling stains.
- Algae and shade masking hail evidence: North-facing shaded slopes grow algae streaks that make hail strikes hard to photograph — documentation needs raking light and close-ups, not driveway photos.
- Aging 1990s roofs: Much of Kingwood and Atascocita was built in the 1980s–2000s. Adjusters scrutinize these claims for "wear and tear," which makes the storm-date verification and test-square evidence in your file the difference between a storm claim and a maintenance lecture.

ACV vs. RCV: The Two Checks, Explained Simply
Most Texas roof claims settle in two payments. The first check is ACV (Actual Cash Value) — the replacement cost minus depreciation for your roof's age. The difference is held back as recoverable depreciation and released when the work is complete and documented (the RCV total). Homeowners who never submit completion paperwork leave that second portion unclaimed. A claim specialist's completion file — final invoice, photos of the finished roof — exists precisely so that money actually reaches you.
One more Texas rule that shapes every claim: your wind/hail deductible is usually a percentage (commonly 1–2%) of the home's insured value, and it is yours to pay. Texas House Bill 2102 makes it illegal for a contractor to waive or absorb it. A specialist who offers to "eat your deductible" is not doing you a favor — they are creating legal exposure for you and cutting the cost out of your roof somewhere you cannot see.
What a Claim Specialist Cannot Honestly Promise
- No guaranteed approvals. The carrier decides. A specialist guarantees the quality of your documentation — nothing more, and anyone promising more is selling.
- No settlement negotiation. In Texas that role belongs to licensed public adjusters and attorneys. A roofer negotiating your settlement is operating outside their license.
- No deductible tricks. See HB 2102 above. Full stop.
- No "free roof" framing. Insurance pays for covered storm damage per your policy terms — deductible, depreciation rules, and all. Honest claim support makes the process documented and complete; it does not make it magic.
Frequently Asked Questions About Roof Insurance Claim Specialists
How much does a roof insurance claim specialist cost?
When the specialist works for the roofing company performing your repair, claim documentation support is typically included as part of the project — the inspection, photo file, scope, and adjuster meeting are how the company earns the build. That is different from a licensed public adjuster, who works only for you and typically charges a percentage of the settlement. Ask any specialist, in writing, which model they are and what they charge before you sign anything.
What is the difference between a roofing claims adjuster and a claim specialist?
"Roofing claims adjuster" almost always refers to the adjuster your insurance company sends — their role is to evaluate the claim for the carrier. A claim specialist is on the documentation side: they inspect, photograph, and scope the damage and meet the adjuster with you. Same roof, same meeting, different employers and different jobs.
How long does a Kingwood roof claim usually take?
In normal volume, expect roughly one to three weeks from filing to the adjuster's scope, then additional time for supplements and scheduling the build. After a major Houston event — the derecho and Beryl are recent examples — adjuster backlogs stretch those timelines considerably, which is another reason to file promptly and arrive with documentation already complete.
Can my roofer negotiate with my insurance company for me?
No. Texas law reserves claim negotiation for licensed public adjusters (and attorneys). Your roofer and claim specialist can document damage, write scopes, meet the adjuster, and supply evidence for supplements — and that documentation is usually what moves a claim — but they cannot legally negotiate the settlement itself, and you should be cautious of any roofer who offers to.
Get Your Claim Documented Before the Adjuster Arrives
Epic Roofing & Construction provides free claim documentation inspections across Greater Houston — including Kingwood, Atascocita, and Humble — with a complete photo file, chalked test squares, and a written line-item scope, and we meet your adjuster on the roof. Straightforward about what we can and cannot do, and your deductible stays exactly where Texas law puts it.
📞 Call (281) 326-9905 — Free Claim Inspection
Or see the full process first: Insurance Claim Roofing in Houston →